Why Next-Day Merchant Account Deposits Matter?
For any business that accepts credit or debit card payments, either online or through a retail location, getting paid is just as important as making the sale.
Imagine that you are running an e-commerce business in Texas that generates roughly around $15,000 in credit card transactions every day. You have suppliers to pay, you need to spend money on advertising campaigns, you need to pay your employees, and you also need to manage your daily operational expenses.
However, your credit card processing revenue takes three to five business days to reach your business bank account. Even though your business is generating money, you may still experience a working capital shortage, and this is simply because the money is tied up in the settlement process.
This is where a merchant account with next-day deposit can make a significant difference for your business. Next-day funding allows eligible businesses to receive funds from successful, processed, and settled credit card transactions on the next business day. However, this is always subject to the merchant account’s funding schedule, applicable cutoff times, banking arrangement, and the conditions that rule the relationship between you and the payment service provider.
For businesses with high transaction volume, seasonal sales, recurring expenses, or demanding supplier payment schedules, getting faster access to money can improve the financial flexibility.
But how do you apply for a merchant account that offers next-day deposit? This is the question that we are going to answer in this post in our merchant account forum.
- What documents are required?
- Can a newly established business qualify?
- Is a high-risk business also eligible for next-day funding?
This forum post explains everything that you must know before you apply with any payment service provider.
Let us first understand what is a merchant account with next-day deposits.
A merchant account with next-day deposit is basically a payment acceptance arrangement that allows an eligible business to receive funds from card transactions on the next business day after the applicable settlement process. When your customer purchases something using his or her credit or debit card, then the transaction goes through several stages.
- In the first stage, the customer submits the payment.
- In the second stage, the transaction is authorized.
- In the third stage, the transaction is included in the merchant settlement batch.
- In the fourth stage, the batch is submitted according to the provider’s cutoff schedule.
- In the fifth stage, the transaction is settled through the relevant banking arrangements.
- In the final, which is the sixth stage, the merchant receives the applicable funds in its nominated business bank account.
The important distinction here is that payment authorization and merchant funding are not the same thing. An authorized transaction does not automatically mean that the money is immediately available in your business bank account.
The timing of the deposit also depends on the merchant account agreement, settlement arrangements, transaction timings, and the receiving bank. The following table gives you a clear understanding of next day funding versus standard funding. But remember that merchant account provider can offer different funding schedules. So make sure that whichever provider you’re working with, ask them if they can offer you next day funding or not before you say yes.
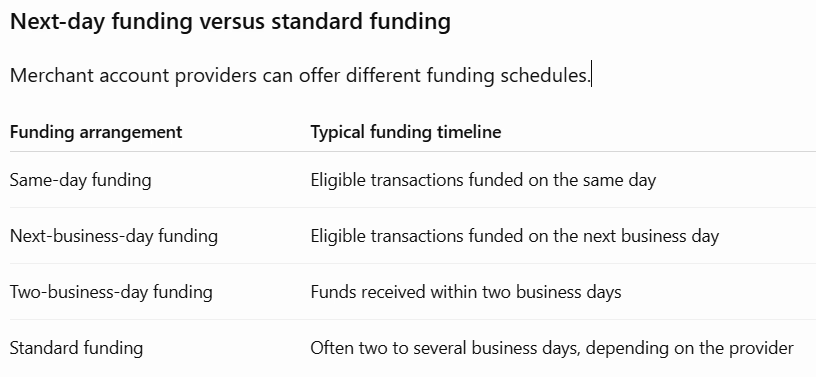
Please note that the above-mentioned table only gives general funding categories and these are not guaranteed timelines. Your actual schedule must be confirmed by your provider.
Let us now understand how does next day merchant account funding works.
Understanding the settlement process will help you choose the right merchant account for your business. Let us consider an example. Suppose your business that sells high-end jewelry and you processesed $80,000 in card payment on Monday. Your merchant account is configured for next day funding, and you choose your settlement batch before the applicable cutoff. Then your funding schedule may look like what you see in the following table.
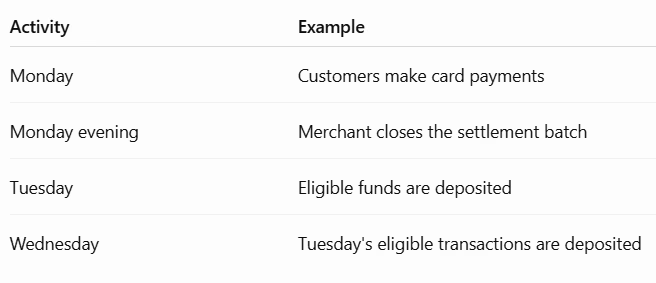
Please note that the above table is only an illustrative example. Actual deposit timing will totally depend on the acquiring and processing arrangements and your bank.
Let us now understand why are cutoff timings so important.
Every merchant account may have a specific settlement or batch closing deadline. For example, one provider in California might require merchants to close their daily batches by 8:30 p.m. Pacific Time, while other may use a different cutoff. If you miss the applicable deadline, then your transaction may actually move into the following settlement cycle and this can delay the deposit by an additional business day.
Before applying, make sure that you ask these important questions to the payment service provider.
- What is the daily settlement cutoff?
- Time zone is applied to your account.
- Is automatic batch closing available?
- Are weekend transactions funded on Monday?
- How are public holidays handled?
- Does the funding schedule apply to all eligible transactions?
All of these questions can help you prevent unexpected cash flow disruptions.
Let us now understand who should apply for a merchant account with next day deposit.
Next day deposit can benefit businesses that depend on predictable access to their credit card processing revenue. An example can include e-commerce business. These are online retailers that frequently need to replenish their inventory. They need to pay suppliers, and they also need to finance the advertising campaign. Faster deposit for these businesses helps them to manage their expenses without relying excessively on working capital facilities.
Subscription businesses that offer membership, software subscription, or recurring services may also benefit from predictable settlement schedules.
Retail stores that often handle daily operating expenses, which may include inventory purchases, rent, wages, and utilities. They can also benefit from next-day funding.
Travel and hospitality businesses, including travel agencies, hotels, and related operators, may have substantial transaction volume and ongoing operational commitment. Their funding requirements should be assessed carefully, particularly when the services are delivered well after payment.
Gaming and adult entertainment businesses may also require merchant account arrangement with such facility so that they can accommodate their transaction volume and operational cash flow requirement. Approval and funding conditions, however, always depend on the business model, jurisdiction, underwriting, and the provider policies.
Some businesses that operate in high-risk industries may have difficulty obtaining conventional merchant account arrangement. Depending upon their business model and underwriting assessment, they may need specialist merchant services with clearly defined settlement schedules.
It is important to know that a high-risk classification does not automatically mean that next-day funding is unavailable. However, it is also important to know that additional conditions, reserves, delayed funding, or transaction restrictions may apply.
Let us now look at what documents do you need to apply for next-day funding account.
When you prepare your documents before starting the application, this can help you in reducing delays. Although the requirements may vary between merchant account providers, but most applications require information about your business, the owners of the company, how the operations take place, and expected transaction activity.
The general checklist includes business documentation such as certificate of incorporation, business registration certificate, company registration number, registered business address, business website, description of products and services, relevant business licenses wherever applicable, business bank account details.
In terms of directors and beneficial owner information, the payment service provider will also ask for the government-issued identification, proof of residential address, ownership structure, detail of directors and beneficial owners, and additional verification documents may also be requested by the underwriting team.
In terms of financial and processing information, you will have to share the recent business bank statement, previous merchant processing statement if available, estimated monthly processing volume, average transaction value, expected monthly transaction value, expected monthly transaction count, and refund and chargeback information if you’re already accepting credit card payments.
The payment service provider will also check your website for operational information. For online businesses, the payment service provider will review the terms and condition, refund and cancellation policy, privacy policy, shipping and delivery policies, customer support contact details, product and service description, subscription and recurring billing terms, if applicable.
It is important to know that the documentation requirements are not identical across providers and industry. A newly established business may not have the historical processing statement, but it should be prepared to provide alternative evidence of business operations and financial positioning. A business plan can help startup entrepreneurs.
Let us now understand how to apply for a merchant account with next day deposit.
A merchant account with faster deposit involves more than just submitting an online form. You should approach the process in a strategic manner.
The first step is to identify your business requirements. Before you contact any payment service provider in the USA, UK, Europe, or Australia, make sure that you establish your expected processing requirements. You should consider the following:
- Where is your company registered?
- Where your customers are located?
- What products or services do you plan to sell?
- What is your expected monthly credit card volume?
- What is your average transaction value?
- Do you want to accept one-time payments or you want to accept recurring payments as well?
- Do you require online payments, physical terminals, invoice payments, or you want all of that?
- Is next day funding extremely essential or would two business days or three business day funding work for you as well?
Having these answers ready can help it make easier for you to identify a suitable merchant account arrangement.
The next step is to identify providers that offer next day funding. Remember that not every merchant account provider offers the same settlement arrangement. Some providers support next day funding while others offer standard settlement schedule or faster funding as an optional service.
When you’re comparing providers, you should look beyond the advertised deposit speed. You should evaluate factors such as availability of next business day funding, settlement cutoff times, supported countries and currencies, supported business industries, monthly and transaction fees, rolling reserve requirements, additional security or verification requirements, bank account eligibility, funding restrictions and conditions. You should never assume that an advertised next day deposit option automatically applies to every business. Always ask for confirmation of the proposed funding arrangement before you sign any agreement.
The next step is to complete the merchant account application. Once you identify the suitable provider, then you’ll have to submit the application and the required business information. The application generally covers company information, director and ownership information, business activities, expected processing volume, transaction characteristics, customer locations, refund and fulfillment processes, bank account details and requested funding schedules. We encourage you to be as accurate as possible when you describe your business. Inconsistent information about transaction volume, business activities, or fulfillment timelines can create unnecessary underwriting delays.
The next step is to complete underwriting and verification. The provider and its relevant banking or processing partner may assess your application, and the review may include business verification, director and beneficial owner verification, financial assessment, website and product review, processing history, transaction and refund patterns, business model and fulfillment assessment, potential financial and operational risk analysis. The purpose here is to establish whether the business meets the provider’s acceptance criteria and what commercial conditions should the processor apply to the account. Depending on the business, additional documents and clarification may be requested by the underwriting team. You must know that approval is not guaranteed and the final decision always rests with the relevant provider or the banking partner.
The next step is to confirm next day funding in writing. This is one of the most important steps and we have seen many merchants ignoring it. Do not rely solely on the salesperson saying that the next day deposits are available. Always ask for the proposed funding schedule and relevant conditions in writing. You should confirm whether the arrangement is next business day or next calendar day funding, the settlement time, the settlement cutoff time, the applicable time zone, whether weekends are excluded, whether public holidays are excluded, whether a rolling reserve applies to your account, whether initial transactions have a different funding schedule, whether the provider can change the funding schedule without your approval, what circumstances can trigger delayed deposits and additional reviews. A merchant account may be approved without being approved for the specific funding arrangement you requested.
Once approved, complete the required onboarding. Depending on the payment acceptance method, this may involve payment gateway integration, hosted payment page configuration, API integration, virtual terminal setup, point of sale terminal configuration, recurring billing setup, test transactions, and bank account verification. You should always follow providers’ technical and security instructions.
The final step is to process transactions and monitor deposits. After activation, begin processing within the approved limits and business parameters, and you should always monitor daily transaction totals, batch closing times, expected funding dates, actual bank deposits, refunds, chargebacks, reserve deductions, and settlement discrepancies. Keep your processing activity consistent with the information supplied during underwriting. If your business experiences substantial growth or changes its operating model, then make sure that you discuss the change with the payment service provider rather than assuming that your existing terms will automatically accommodate it.
Can high-risk businesses get merchant accounts with next-day deposits?
Yes, some high-risk businesses may qualify for next-day funding, but the eligibility is always assessed individually by the payment service provider. Traditional merchant account options are not always suitable for every business model. Businesses that operate in industries that have elevated financial, regulatory, fulfillment, or dispute risk may require specialist merchant services.
Examples of such industries include online gaming, forex, financial services, money transfer companies, cryptocurrencies, CBD businesses, vape, tobacco, cigars, nutritional supplements, vitamins, dating services, skill gaming, and certain travel-related businesses. However, it is also important for you to know that industry eligibility can vary significantly by provider and jurisdiction.
What affects next-day funding eligibility for high-risk merchants?
There are several factors that can influence the proposed funding terms. The first one is processing history. A merchant with established processing history can easily demonstrate transaction patterns, refund levels, and business stability.
The next factor is monthly processing volume. Providers, they actually evaluate expected monthly volume and whether it is consistent with the business’s operational capacity or not. Average transaction value. Large transactions may require additional assessment depending on the business model.
Chargeback and refund history. Previous disputes, account closure, refunds, and transaction reversal can definitely influence underwriting and funding conditions.
Fulfillment timelines. A business delivering a product immediately may present a different kind of risk profile to the underwriters from one that is collecting the payment months before the service will be provided.
Financial position. Bank statements, revenue information, and other financial documents related with the company and the directors can help providers evaluate the financial strength of the company.
Rolling reserve. Some high-risk merchant accounts may include rolling reserve or other form of security. A rolling reserve means that an agreed portion of the processed funds will be withheld for a specific period of time, and this is done to cover the potential refund, chargebacks, or other liability. For example, if you are a merchant based out in Philadelphia and you process roughly around $20,000 and have a hypothetical 10% rolling reserve, that means $2,000 may be withheld according to the agreed reserve terms. The remaining eligible funds may still be funded according to the agreed settlement schedule. The actual reserve percentage, duration, and the release condition must also be confirmed with the payment service provider in writing. Next-day funding does not necessarily mean that 100% of your gross processing volume will be deposited the following business days.
How Much Does a Merchant Account with Next-Day Deposits Cost?
These two terms are often used interchangeably in marketing, but they actually describe different funding arrangements. The following table gives clear information about the key differences.

For most businesses, next business day funding may provide a practical balance, which is between accessibility and operational convenience. Same day funding may be worth considering if your business has more immediate cash flow requirement and does qualify for the service. You should always compare the actual funding conditions rather than relying on the name of the service.
Let us now look at common reasons next day merchant deposits get delayed.
Even when your merchant account is configured for next day funding, there can be certain situations which can affect the expected deposit.
Missing the settlement cutoff. If a batch is submitted after the provider’s cutoff time, then the transactions may enter the next settlement cycle.
Weekend or public holidays. Many standard next business day funding arrangements, they operate on banking business days rather than calendar days. A Friday transaction may therefore be funded only on Monday, subject to the provider’s schedule.
Incomplete verification. Outstanding business verification, bank account verification, or requested documentation, these all can delay account activation or funding.
Unexpected transaction activity. A sudden increase in the processing volume, usually large transactions or activity inconsistent with the approved business profile, may also trigger additional review.
Refunds and chargebacks. Disputes, refunds, and reversals, they all can affect the amount ultimately deposited.
Reserve requirements. If your merchant account agreement includes a rolling reserve or other holdback terms and condition, then the full transaction amount may not be included in the next deposit.
Banking delays. Once funds have been released, the receiving bank’s processing schedule may also affect when they become visible and available. If a deposit is delayed, contact the merchant account provider and request a statement level explanation rather than assuming that the payment has been lost.
There are certain questions that you must ask before signing an agreement, use the following checklist.
- Do you offer next business day funding for my specific business model or not?
- Is next day funding included in the quoted pricing? Check the agreement.
- What is the daily cutoff timing?
- What is the daily settlement cutoff timing?
- Which time zone applies?
- Are weekends and bank holidays excluded?
- Is there an initial funding delay?
- Will my account have any kind of rolling reserve or fixed reserve?
- Can the provider impose additional funding holds?
- Are there any monthly minimums or additional account charges?
- Make sure you get all of this in writing.
- Does the funding arrangement apply to all approved payment methods?
- Can the funding schedule change after activation?
- What happens if my processing volume increases substantially?
A provider that is ready to answer all these questions clearly is easier to evaluate than the one that simply advertises fast deposit.
How QuadraPay can help businesses find suitable merchant account solutions?
Choosing a merchant account is not simply about finding the lowest processing rate. Businesses like yours should consider whether the proposed solution matches your industry, transaction profile, operating countries, expected volume, and cash flow requirements. At QuadraPay, we operate a merchant account consultancy and a payment reseller business, and we help businesses in exploring suitable merchant account solutions through our network of partner processors. We serve businesses in US, UK, Europe, Australia, and New Zealand.
We can potentially assist your business in understanding your merchant account requirements, identifying potential suitable merchant account options, preparing business and underwriting documentation, presenting application to relevant processing partners, understanding proposed processing and settlement terms, coordinating the application related communication, and providing assistance in terms of integration after account activation.
For businesses that are looking forward to get next day deposit, we can help them to identify potential solutions and clarify the funding arrangements available through partner processors.
Looking for a high risk merchant account with next day deposit?
If your business operates in high risk industry, then finding a suitable merchant account arrangement may require more than just detailed assessment. We can potentially help you understand what information is required and help you explore potential options based on your business profile. For acceptance, pricing, reserve, funding schedules, all of these are determined by the relevant processing partner subject to their underwriting and internal terms and conditions.
Get started with QuadraPay today by filling the short form on our website.
Frequently asked questions about merchant account with next day deposit.
Can I get a next business day funding merchant account?
Yes, some merchant account providers do offer next business day funding. This is only offered to eligible businesses. The availability totally depends on the provider, underwriting profile, settlement arrangements, and bank processing timings.
How long does it take to receive money the next day with next day funding?
Eligible transactions may be deposited the business day after eligible transactions may be deposited on the next business day after the applicable settlement process. Cutoff times, weekends, holidays, and bank processing schedules, these all can affect the actual arrival time.
Can a new business qualify for next day merchant account funding?
Potentially, yes. However, a new business may be subject to additional underwriting requirements, and this is because it does not have any established processing history. And that is why the provider may request business plans, bank statements, supplier information, and other supporting documents.
Can high-risk merchants get next-day deposit?
Some high-risk businesses may qualify for it. However, their applications are also assessed individually, and additional conditions such as rolling reserve, transaction limits, and enhanced verification may also apply.
Does next-day funding means I receive 100% of my transactions?
No. Transaction fees, refunds, chargebacks, rolling reserves, and other contractual deductions, they all may affect the final amount that is deposited to your business bank account.
Are next-day deposits available on weekends?
It totally depends on the provider and specific funding arrangement. Many standard next-day business schedules exclude weekends and public holidays, although certain providers may offer alternative funding arrangements.
Is next-day merchant account funding more expensive?
Not always. Some providers include next-day funding into their standard pricing, while others may charge additional fees for expedited funding. That is why always request a complete fee schedule from the payment service provider.
What is the difference between settlement and funding?
Settlement basically refers to the process through which the payment transactions are financially reconciled and the funds are transferred through the relevant payment arrangement. Funding, however, refers to the deposits of the eligible funds into the merchant’s nominated business bank account.
Can I change my existing merchant account to next-day funding?
It may be possible, and for that you must contact your existing provider and ask whether the account is eligible for a different funding schedule. These changes may require additional review, contractual approval, or revised pricing.
Does next-day funding guarantee that the money will be available the following morning?
No. Next-day funding generally refers to funding schedule, and it is not a guaranteed deposit hour. The actual time totally depends on settlement cutoffs, transfer arrangements, and the receiving bank.
Can international businesses apply for next-day merchant account funding?
Some international businesses may qualify, but it depends on their country of incorporation, operating location, bank account jurisdictions, industry, and the provider coverage. International settlement arrangements may have different timelines.
What documents should I prepare before applying?
Typically, businesses should prepare incorporation documents, director identification, proof of address, business bank account, website information, processing estimates, and relevant licenses. Additional requirements totally depend on the provider.
Can I receive next-day deposit if I have rolling reserve?
Potentially. A rolling reserve and next-day funding schedule are separate contractual arrangement, and the eligible balance may be deposited on the agreed schedule when the reserve portion is withheld according to the arrangement.
Is next-day funding the same as instant settlement?
No, next day funding simply means that eligible funds are deposited on the next business day. Instant settlements generally refers to a faster transfer arrangement. However, they are subject to its own eligibility and processor internal conditions and terms.
How can QuadraPay help me apply?
QuadraPay helps businesses in understanding their merchant account requirements, prepare applications, and explore potential solutions through relevant processing and acquiring partners. But the final approval and funding conditions, they are always determined by the relevant partner of ours.
Conclusion, choose a merchant account that matches your cash flow requirement.
Next day merchant account deposit can help businesses in managing working capital, pay suppliers, and maintain smoother daily operations. However, the fastest advertised funding schedule is not necessarily the best solution.
Before applying, you should always evaluate the provider settlement cutoff, funding conditions, processing fees, reserve requirements, and the suitability for your specific industry. And for businesses that are operating in high-risk sectors, finding an appropriate merchant account solution definitely requires particular attention to underwriting and settlement terms.
The best approach is to understand your processing requirements first, then to prepare your accurate documentation, and further compare funding arrangement before you commit to any payment service provider.
Do you need help in exploring a merchant account with next day deposit? Then you should speak with a QuadraPay expert about your business requirements. We will help you explore potential suitable merchant account solutions through our partner processors.